Home improvement projects can significantly increase a property's comfort, functionality, and long-term value. Whether you're replacing an aging roof, installing energy-efficient siding, remodeling a kitchen, or finishing a basement, financing often becomes one of the biggest decisions homeowners face.
A home equity loan for home improvement is one of the most common financing options because it typically offers lower interest rates than unsecured personal loans or credit cards. However, understanding home equity loan for home improvement rates requires more than simply comparing advertised percentages. Loan rates depend on your credit profile, available home equity, loan amount, repayment term, lender policies, and broader economic conditions.
This guide explains how home equity loan rates work, what influences them, how they compare with other financing options, and how homeowners can make informed borrowing decisions.
What Is a Home Equity Loan?
A home equity loan allows homeowners to borrow against the equity they've built in their property.
Home equity is generally calculated as:
Current Home Value − Remaining Mortgage Balance = Home Equity
For example:
| Home Value | Mortgage Balance | Available Equity |
|---|---|---|
| $500,000 | $250,000 | $250,000 |
| $400,000 | $180,000 | $220,000 |
| $650,000 | $300,000 | $350,000 |
Lenders typically do not allow borrowers to access all available equity. Instead, they establish maximum combined loan-to-value (CLTV) limits based on lending guidelines and borrower qualifications.
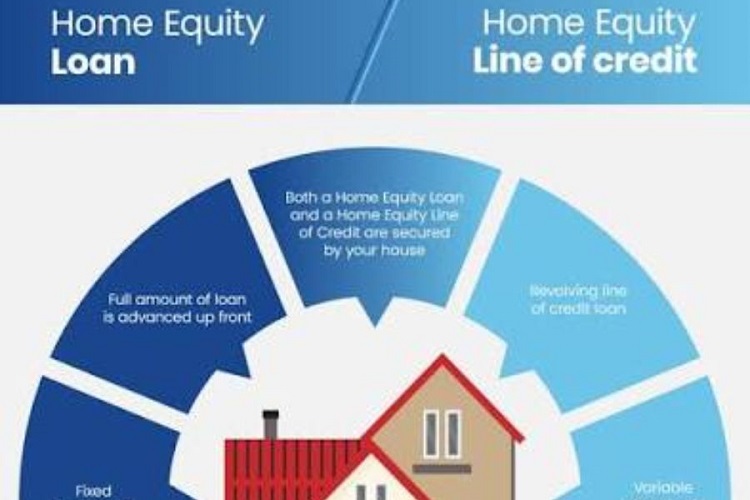
Unlike a home equity line of credit (HELOC), a home equity loan provides a lump-sum payment with a fixed interest rate and predictable monthly payments.
This makes it particularly suitable for projects with known costs, such as:
- Roof replacement
- Complete siding replacement
- Window upgrades
- Kitchen renovation
- Bathroom remodeling
- HVAC installation
- Solar-ready roofing improvements
- Foundation repairs
- Major landscaping
- Room additions
What Are Home Equity Loan for Home Improvement Rates?
Home equity loan rates represent the interest charged on borrowed funds.
Unlike adjustable-rate financing, most home equity loans feature:
- Fixed interest rates
- Fixed repayment schedules
- Fixed monthly payments
- Fixed loan terms
Because the loan is secured by the borrower's home, interest rates are generally lower than unsecured financing.
Actual rates vary continuously based on:
- Federal interest rate environment
- Individual lender pricing
- Credit score
- Debt-to-income ratio
- Loan amount
- Loan term
- Home equity available
- Property type
- Geographic market
Rather than focusing solely on the advertised rate, borrowers should compare the Annual Percentage Rate (APR), which reflects both interest and many financing costs.
Factors That Affect Home Equity Loan Rates
Several variables influence the interest rate offered by lenders.
Credit Score
Borrowers with stronger credit histories generally qualify for more favorable rates.
Lenders evaluate:
- Payment history
- Credit utilization
- Length of credit history
- Recent credit inquiries
- Existing debt obligations
Loan-to-Value Ratio (LTV)
The more equity a homeowner has, the lower the lender's risk.
Lower LTV ratios often qualify for better pricing.
Debt-to-Income Ratio (DTI)
Lenders assess whether monthly debt payments remain manageable after adding the new loan.
Lower DTI ratios typically improve approval chances.
Loan Amount
Some lenders offer different pricing depending on:
- Small loans
- Medium-sized loans
- Large renovation financing
Loan Term
Longer repayment periods usually result in:
- Lower monthly payments
- Higher total interest paid
Shorter repayment periods generally:
- Increase monthly payments
- Reduce total borrowing costs
Property Characteristics
Rate offers may also vary depending on:
- Primary residence
- Second home
- Investment property
- Condominium
- Manufactured housing
Typical Home Improvement Projects Financed With Home Equity Loans
| Project | Suitable for Home Equity Loan? |
|---|---|
| Roof replacement | Yes |
| Siding replacement | Yes |
| Window replacement | Yes |
| HVAC system | Yes |
| Kitchen remodel | Yes |
| Bathroom remodel | Yes |
| Home addition | Yes |
| Basement finishing | Yes |
| Foundation repair | Yes |
| Driveway replacement | Yes |
Projects involving significant upfront costs often align well with lump-sum financing.
Advantages of Using a Home Equity Loan
Many homeowners choose home equity loans because they offer several practical benefits.
Predictable Payments
Fixed monthly payments simplify budgeting throughout the repayment period.
Competitive Interest Rates
Because the loan is secured by real estate, interest rates are often lower than unsecured financing.
Lump-Sum Funding
Large renovation projects usually require immediate access to funds.
Examples include:
- Complete roof replacement
- Exterior siding installation
- Structural repairs
- Whole-home renovations
Potential Home Value Improvements
Quality renovations may improve:
- Market value
- Energy efficiency
- Curb appeal
- Property durability
However, increased home value is never guaranteed and depends on local market conditions and project quality.
Potential Drawbacks
Homeowners should also understand the risks.
Your Home Serves as Collateral
Failure to repay the loan could result in foreclosure.
Closing Costs
Some lenders charge:
- Origination fees
- Appraisal fees
- Title fees
- Recording fees
Always compare total borrowing costs rather than focusing solely on interest rates.
Long-Term Debt
Financing spreads project costs over many years.
While monthly payments may be manageable, total interest paid can become substantial over time.
Home Equity Loan vs HELOC vs Personal Loan
| Feature | Home Equity Loan | HELOC | Personal Loan |
|---|---|---|---|
| Interest Rate | Usually fixed | Often variable | Usually fixed |
| Funding | Lump sum | Revolving credit | Lump sum |
| Monthly Payment | Fixed | Variable | Fixed |
| Collateral | Home | Home | Usually none |
| Best For | One-time renovations | Ongoing projects | Smaller improvements |
Each financing option serves different homeowner needs depending on project size and budgeting preferences.
Home Improvements That May Increase Property Value
Not every remodeling project produces the same return.
Common improvements that often attract buyers include:
- Roof replacement
- New siding
- Energy-efficient windows
- Kitchen updates
- Bathroom renovations
- Garage improvements
- Exterior painting
- Improved insulation
- HVAC upgrades
- Landscaping
The actual return depends on:
- Neighborhood
- Market demand
- Construction quality
- Material selection
- Local housing conditions
Energy-Efficient Improvements
Many homeowners use home equity loans to finance energy-saving upgrades.
Examples include:
- Better attic insulation
- ENERGY STAR-certified windows
- High-efficiency HVAC systems
- Air sealing improvements
- Cool roofing materials
- Energy-efficient doors
These improvements may reduce long-term utility costs while improving indoor comfort.
Homeowners should also explore available rebates or incentive programs offered by utilities, state agencies, or federal initiatives before financing a project.
How to Qualify for Better Home Equity Loan Rates
Improving borrower qualifications before applying can make a meaningful difference.
Strengthen Your Credit
Pay bills on time and reduce outstanding revolving debt where possible.
Build Additional Equity
Making extra mortgage payments over time can increase available equity.
Compare Multiple Lenders
Obtain loan estimates from several institutions, including:
- Banks
- Credit unions
- Online lenders
Comparing offers helps identify differences in:
- Interest rates
- APR
- Fees
- Closing costs
- Repayment flexibility
Avoid Taking on New Debt
Large purchases before applying may negatively affect debt-to-income ratios.
Questions to Ask Before Choosing a Lender
Use this checklist during the application process.
- Is the interest rate fixed?
- What is the APR?
- Are there closing costs?
- Is an appraisal required?
- Are there prepayment penalties?
- What repayment terms are available?
- How quickly are funds disbursed?
- Is automatic payment discount available?
- What documentation is required?
Common Mistakes Homeowners Make
Avoid these frequent borrowing mistakes.
- Borrowing more than necessary
- Ignoring total interest costs
- Comparing only advertised rates
- Not reviewing closing costs
- Underestimating renovation budgets
- Hiring contractors without proper licensing or insurance
- Beginning construction before financing approval
- Skipping written contracts
Choosing the Right Contractor
Financing is only one part of a successful home improvement project.
Before signing a contract:
- Verify licensing where required
- Confirm insurance coverage
- Request written estimates
- Review references
- Understand warranty coverage
- Read the contract carefully
- Clarify payment schedules
- Confirm permit responsibilities
Organizations such as the National Roofing Contractors Association (NRCA) recommend using qualified roofing professionals for roof replacement projects, while local building departments enforce applicable building codes based on the International Code Council (ICC) model codes as adopted by the jurisdiction.
Maintenance After Your Home Improvement Project
Protecting your investment helps maximize long-term value.
Exterior Maintenance Checklist
- Inspect roofing annually
- Clean gutters regularly
- Check siding for damage
- Seal exterior gaps
- Maintain proper drainage
- Inspect flashing
- Trim overhanging tree branches
- Address water intrusion promptly
Routine maintenance can extend the service life of many building components and reduce the likelihood of costly repairs.
Insurance Considerations
Some improvements may affect homeowners insurance.
Notify your insurance provider after completing major renovations such as:
- Roof replacement
- Structural additions
- Detached garages
- Finished basements
- Solar installations
Updated replacement costs and property features may require policy adjustments.
Frequently Asked Questions
Is a home equity loan better than a personal loan for home improvement?
For homeowners with sufficient equity, a home equity loan often offers lower interest rates than unsecured personal loans. However, it places the home at risk if payments are not made.
Are home equity loan rates fixed?
Many home equity loans have fixed interest rates, though loan products vary by lender. Always review the loan agreement before signing.
Can I use a home equity loan for any home improvement project?
In most cases, lenders do not restrict home improvement projects as long as the loan meets their underwriting requirements and the borrower qualifies.
Does improving my home increase its value?
Many improvements can enhance resale appeal and market value, but the increase depends on project quality, local market conditions, buyer demand, and the type of renovation completed.
Should I compare APR instead of interest rate?
Yes. APR provides a more complete picture of borrowing costs because it includes the interest rate and many applicable lender fees.
Conclusion
A home equity loan can be an effective financing solution for homeowners planning major renovations such as roofing, siding replacement, kitchen remodeling, or energy-efficiency upgrades. Its fixed interest rate, predictable monthly payments, and access to a lump sum make it especially well suited for projects with defined budgets.
When evaluating home equity loan for home improvement rates, avoid focusing solely on the advertised interest rate. Compare APRs, understand all fees, review repayment terms, and consider how the loan fits within your overall financial goals. Just as important, choose qualified contractors, obtain detailed written estimates, and maintain your improvements to protect both your investment and your home's long-term value.
Before committing to financing, review guidance from reputable organizations such as the U.S. Department of Housing and Urban Development (HUD), the Federal Housing Administration (FHA), the U.S. Department of Energy (DOE), the Environmental Protection Agency (EPA), and ENERGY STAR. These resources provide valuable information on responsible borrowing, energy-efficient upgrades, and maintaining a safe, durable, and valuable home.